


This is not an AI-generated report. It’s written from our original thoughts and independent research.
The key areas we address are
- Huge AI capital spending and its risk to financial markets
- Elevated world uncertainty the market is ignoring
- An anaemic SA economy poised to grow
- The biggest risk to SA – ANC succession
- SA and Emerging Markets offer more attractive investment opportunities relative to developed markets.
AI is clearly the biggest “buzz” in the global business world today. And rightfully it should be. It’s another “life-changing” invention, such as the internet and electricity, that will affect us all into the future.
In short, we believe AI should have a net positive effect on the world as it stimulates economic growth. However, the fear is that the associated prosperity will further widen the wealth gap, one of the biggest problems challenging the world today.
While AI has the potential to lift global productivity, it also can widen existing gaps in economic performance and competitiveness. Non-adopters will soon fade away.
Its initial prosperity is being realised across global stock markets, which have soared to record highs in 2026 as investors chase its potential rewards. At this early stage, these rewards are difficult to measure. But the risks are slower monetisation, disappointing productivity gains or overinvestment in AI infrastructure, which will strain high equity valuations and capital spending plans.
Massive AI capital expenditure is a big concern
The internet expenditure bubble in 2000 was mainly financed by debt and equities, fuelling its collapse. AI expenditure has initially been financed from internal cashflows. Currently, the massive AI infrastructure spend has forced AI companies to start raising significant debt through bond issuance, which accounts for as much as a fifth of the record total bond issuance in 2026. This ramps up the risk in these AI shares, which now make up 30% of the US market.
The jury is still out on whether the AI Mega-scalers (Meta, Google, Microsoft, Amazon) will achieve an acceptable return on their massive capital expenditure.
US Capital Spending per industry in 2026 ($m)

It’s expected that AI companies will invest over $1 trillion in 2027 in building AI processing capacity. In the short term, these huge infrastructure and energy demands should stoke inflation, but over the longer term, AI should be deflationary due to productivity improvements.
In conclusion, as with the internet, the biggest beneficiaries will be broad-based businesses, which will become more efficient and more profitable. Slow AI adopters will be left behind.
High uncertainty is not concerning the market
Global uncertainty remains dangerously elevated relative to today’s high market valuations. This friction matters: uncertainty creates investment risk and drives valuations down. Yet the market is currently acting as if that risk doesn’t exist.
Uncertainty spiked at the start of 2025 with the introduction of Trump’s tariffs. Thereafter, continued policy changes and now heightened geopolitics, including the US/Iran war, have kept uncertainty at abnormally high levels. This is bad for business.
World Uncertainty Index

Heightened geopolitics is reducing global economic growth
Global wars (Ukraine, Middle East), China/Taiwan tensions and a divisive US are negative for global growth.
Supply-side disruptions and high tariffs raise costs and deepen economic fragmentation. This all leads to higher energy prices, persistent inflation and elevated uncertainty, which is creating a more challenging environment for businesses and policymakers.
Consequently, global growth is expected to slow to 2.9% in 2026. Interest rates should largely remain unchanged in 2026, despite the recent inflation pressures from higher oil prices. Notably, although investment markets were expecting a full 1% interest rate cut at the start of 2026, they have not reacted negatively to the prospect of no cuts this year.

Higher oil prices will keep inflation up
The protracted US/Iran conflict is disrupting 10% of the world’s oil supply and vital chemicals, pushing up global inflation. This raises the risk of stagflation, where higher inflation combines with lower economic growth.
Brent Oil Price

Trump is still influencing market sentiment
Despite Trump’s ongoing policy changes, he still appears to support a positive investment market narrative. But the reach of his influence may be curtailed in November with a probable decline in Republican support in the mid-term elections.
The US mid-term election could see some major power shifts, with Trump’s Republicans likely to lose their majority in Congress and possibly the Senate too. Either loss would reduce Trump’s power and hopefully restore more rational policymaking.
Odds of Democrats winning the House (Congress) and the Senate

The SA economy is weak but poised for growth
The SA economy continues to disappoint with GDP growth expected to be similar to last year at 1.1%. This is despite numerous improvements across crucial government departments, such as rail, ports, electricity and home affairs, plus lower interest rates, down 1.25% from June 2024. With these improvements, why the poor growth?
The main problem is that investment in South Africa’s infrastructure remains very weak. Gross fixed capital formation declined in the first quarter of 2026, despite a weak base of just 13.7% of GDP in 2025 and 14.2% in 2024. The National Development Plan targets a 30% investment rate: the threshold required to drive economic growth above 4% and meaningfully reduce the 32.7% unemployment rate.
The crux of it is that low investment is due to major political uncertainty, discussed below, and an inefficient government.
The SA positives
There is a large increase in private participation in ports, rail and electricity which is driving much needed and welcomed infrastructure improvements.
SA has been removed from the Financial Action Task Force grey list, which will improve our foreign investment appeal.
Foreign rating agencies Fitch, Moody’s and S&P have recently upgraded our sovereign credit ratings. This will support much-needed foreign investment flows, although these flows remain modest for now.
Credit Rating Agency ratings of SA Debt

A positive municipal election outcome in November, further reducing the ANC’s influence, should encourage more foreign investment inflows.
US and SA relations are improving with AGOA (African Growth and Opportunity Act) extended to year end. This should be extended further.
Although inflation spiked to 4.5% in May due to higher oil and chemical prices, the outlook into 2027 is positive with inflation expected to decline back to around 3.5%. This should deter interest rate increases and pave the way for further cuts in 2027.

SA is poised for strong growth if a stable political environment materialises.
State of SA politics remains a major investment concern
2026 has had a relatively stable political environment, most notably with the GNU holding. There have also been some positive moves, such as:
- Operation Vulindlela (OV) making good overall progress
- The Public Service Amendment Bill has been signed into law – this should bar “cadre deployment” in the public sector
- Benign labour relations – Strikes have been near an all-time low
- An improvement in US and SA relations, with the extension of AGOA to year end
- A smooth passing of the budget
- The DA introducing more modern and dynamic leadership – The newly elected top 10 leaders are younger and more demographically diverse, led by the charismatic Geordin Hill-Lewis
ANC succession is most important to investors
This is the single biggest concern cited by SA investors, which we echo.
A new ANC leader should be elected in December 2027, with campaigning to start in the new year. The main candidate is Paul Mashatile (Deputy President) who, if elected, would be a disastrous selection given his perceived preference for the EFF as a coalition partner, rather than the DA.
He will be challenged by a Ramaphosa-endorsed candidate, though who that will be remains uncertain. Front runners are currently Thoko Didiza (Speaker of Parliament), Fikile Mbalula (ANC Secretary General) and hopefully Patrice Motsepe (Businessman and Ramaphosa’s brother-in-law).
The municipal elections in November will be a crucial progress gauge for all parties since the ANC lost its majority in 2024. Various polls point to the ANC’s vote declining further into the mid-30% range and the DA advancing further, closer to 30%. But the outcome of the JHB metro will be a major focus point as the ANC is likely to be defeated by the DA.
Polling in JHB

Although a loss for the ANC in JHB would be a major boost for the DA, it would be negative for the anti-Ramaphosa camp in the ANC and would give more gravitas to a Ramaphosa endorsed candidate in the 2027 ANC leader race.
In conclusion, it is vital that the next ANC leader partners with the DA after the 2029 election, where we assume the DA and ANC in aggregate will achieve a majority vote.
How much longer does the Rand remain strong?
Over the last three years, the Rand/Dollar has strengthened 17% to 16.3 from 19.7, which has been assisted by a weakening US dollar.
US Dollar Index

The Rand’s current resilience is in question
After the Rand’s strengthening in 2025 to 16.5 from 19.5, the Rand has been firm despite the disruptions from the US/Iran war, weaker precious metal prices off a high base, and a recently stronger US dollar.
The sharp rise in precious metals last year (gold up 70% and platinum up 100%) produced a current account surplus (money inflows exceeding outflows), and increased revenue collections to bring some welcome relief to the spiralling government debt. This primarily drove the Rand/Dollar to 16.5 from 19.5 last year.
SA Current Account

We’ve been positive on the Rand, but its persistent strength in 2026 is unwarranted given a weakening global and local economic outlook this year, coupled with an uncertain political climate with municipal elections at year end.
We believe the Rand/Dollar rate should fundamentally be around 17.50. This reflects a purchasing power parity (PPP) of 15.2, plus a 15% judgemental risk adjustment premium. This premium is down from a previous implied 30% in 2024, primarily due to the improved government debt outlook from the new fiscal consolidation policy and improved revenue collections.
Rand/Dollar Purchasing Power Parity (effective Exchange Rate)

The Prosperity Fund continues to produce solid returns
The fund produced a steady 13.1% return over the last 12 months, which supports its solid 10-year track record of average compound growth of 10.1% p.a.

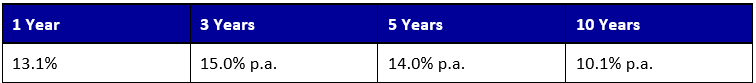
The fund prioritises capital preservation through conservative management. It is designed for investors seeking a balanced portfolio that includes local and international exposure and generates consistent investment returns. The fund reflects Investonline’s in-house market views, which we aim to replicate across different investment risk strategies for our clients.
Its unique investment management style primarily involves taking short-term tactical positions in asset classes that are irrationally priced, based on a combination of top-down and bottom-up fundamental research. To a lesser extent, longer-term strategic positions are incorporated when major market opportunities are identified.
Market Outlook
The global stock market can be separated between the US and the rest of the world, mainly due to the strong rise of the US Megacap 8 (AI-investing) companies, which comprise a massive 30% of the US stock market capitalisation.
The strong performance of the Megacap 8 takes the US market into expensive valuation territory. Stripping out the US, the rest of the world trades at a forward P/E of 14x, which is reasonable and offers many attractive opportunities around the world.
MSCI All World ex US and US forward P/E ratio

The current high US valuations are supported by high earnings forecasts, which may not materialise, given their abnormally high operating profit margins and the uncertain profits from the massive capital expenditure in AI.
US Company and Megacap 8 Profit Margins

Current long-term US earnings growth forecasts are 20%, exceeding the 2000 internet bubble growth forecasts of 18%, which did not materialise. Over the last 40 years, average EPS growth forecasts have been 13%, but actual growth has averaged only 7%.
US 12 months earnings growth forecasts (%)

Therefore, we believe US markets are expensive and risky in a highly uncertain environment with mounting inflation concerns.
There are far more attractive areas to invest over the medium term, such as emerging markets and South Africa.
Country Forward P/E ratios

SA equities offer good value
SA equities, on a forward P/E of 8x, are cheap despite the weak economic growth this year. The key catalyst to unlock this value is a positive municipal election in November, which recent polls suggest is increasingly probable.
A stable political outlook is essential for meaningful investment inflows and an upward re-rating of the JSE.
JSE ALSI (All-Share Index) Forward P/E ratio

With US market valuations high, we still prefer emerging markets and SA equities. We also prefer active funds over passive funds. Passive funds are vulnerable to the market’s high concentration risk unwinding, while active funds should be able to take advantage of the many value opportunities that still exist.
Review your investment strategy
With gaps in global investment valuations widening, it’s essential to ensure that your investment portfolio is properly balanced and aligned with your personal risk profile to achieve your financial goals. Regularly review your financial plan to ensure it remains up to date. It is crucial that the risk you take in your investment portfolio aligns with your financial plan, particularly as you approach or enter your retirement years.
